

News | Inclined Rolls Out Support for VUL

Note from Executive Editor, Bobby Samuelson
We are trying out new types of content, including less analytical but more frequent news-type articles. Paul Hanley is spearheading the idea. The article below is an example of this new type of content. We realized, after publishing it, that it sounds like a commercial for Inclined – that was not the intent. The Life Product Review has never and will never receive compensation for running a piece of content. My position on the Board of Inclined, as disclosed in any previous article that mentions Inclined, had nothing to do with this article. Paul was the one who spotted the new support for VUL and decided to cover it in a news brief.
The newsworthy nature of Inclined rolling out support for VUL is simply that it hasn’t ever been done before – and we hope that other providers will come to the table with cash value collateralized lending as well! It opens up a whole new aperture for using VUL policies as a part of a holistic financial plan by allowing access to the cash without liquidating positions, as we discussed in a previous article.
The fintech startup Inclined Technologies, based in Sausalito, CA, has just rolled out support for Variable UL policies with their iLOC (‘Inclined Line of Credit’). This is an insurance-backed line which uses policy cash surrender value as collateral for the company’s highly sophisticated, digital-first lending platform. The iLOC offers enhanced access to policy cash value by seamlessly connecting clients and advisors with partner banks.
Starting this week, policyholders with Northwestern Mutual can now open an iLOC to borrow against VUL cash values. Although Inclined allows clients to combine different policies and product types across multiple carriers into a single iLOC (or add a policy to an existing line), there must be a separate line for VUL due to its higher risk profile—with a maximum loan-to-value ratio of 50%.
The iLOC gives access to policy cash value either via web browser or mobile app, bypassing the need to call in to the carrier or provide loan paperwork with wet signatures. Processing times are very short, with transfers generally hitting the policyholder’s bank in one business day.
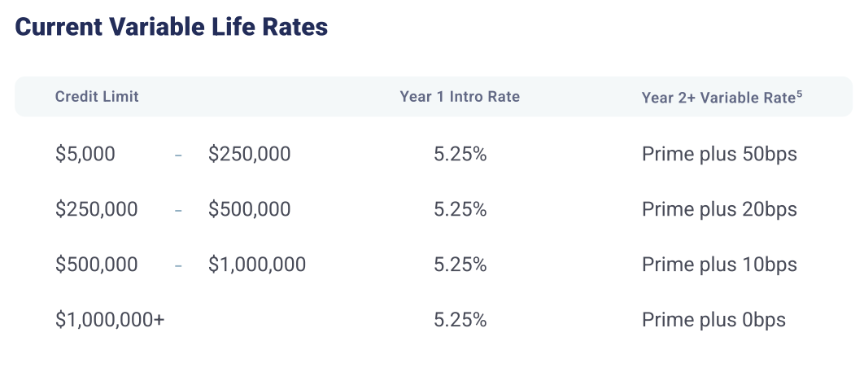
Interest rates for the iLOC are based on Prime—plus or minus a spread depending on the credit limit amount and collateralized product type. The maximum rate is Prime plus 50bps, with a current introductory rate of 5.25% for the first year which applies across all rate tiers:
Traditionally, support for VUL has been nearly non-existent among third-party lenders, as most prefer to collateralize Whole Life because of its guaranteed growth and low-risk profile. According to Inclined co-founder and CEO Josh Wyss, one of the major technical challenges in building out support for VUL is that real-time data feeds need to be established with each carrier to enable daily monitoring of the volatile account values.
While annual or semi-annual reviews of Whole Life policies are often sufficient, lenders need to keep a closer eye on VUL account values due to the inherent investment risk. But according to Wyss, many carriers do not feel a sense of urgency in working to establish a linkage with the pre-configured technology infrastructure that Inclined provides—despite that third-party lending has tangible benefits for insurers themselves.
Increasingly, agents are positioning insurance-backed lines of credit at the point of sale to boost production by offering clients a more streamlined way to access their cash value. However, Wyss says that infrastructure linkage will remain a low priority for many carriers until enough individual producers voice their support for collateralized lending arrangements.
With the addition of VUL, the iLOC now accommodates a full suite of cash value products, including Variable Executive and Comp Life, Whole Life, as well as traditional and Indexed UL. Inclined’s platform currently supports five top mutuals: Guardian, MassMutual, New York Life, Northwestern Mutual and Penn Mutual, and Wyss says the company is eager to engage with other carriers to expand their presence further across the space.
For now, Northwestern Mutual is the only carrier available for VUL collateralization with the iLOC. In the meantime, clients and advisors remain somewhat at the mercy of the other carriers to get on board with implementing the minimal technological requirements to support third-party lending with Inclined—especially on variable contracts.
At TLPR, we have discussed how insurance-backed lines of credit do present some unique lending scenarios that are important for policyholders and advisors to keep in mind—particularly with VUL.
In #460 | Policy Management with Cash Value Lines of Credit, we spell out several different ways that third-party lines can help optimize for policy accumulation with VUL. However, it is important to be aware that when a life insurance contract is collaterally assigned to a lender, it precludes the owner from taking low- or no-cost traditional policy loans directly from the carrier to reduce arbitrage risk—which is a key consideration when managing heavily-loaned policies.
Insurance-backed lines of credit are still a fairly niche offering which is only slowly gaining traction across the life insurance space. Most lenders maintain quite high minimum credit limits that have left many policyholders unable to qualify for lending. The iLOC is a highly accessible line which offers a very reasonable minimum credit limit with a wide variety of product types available for collateralization.
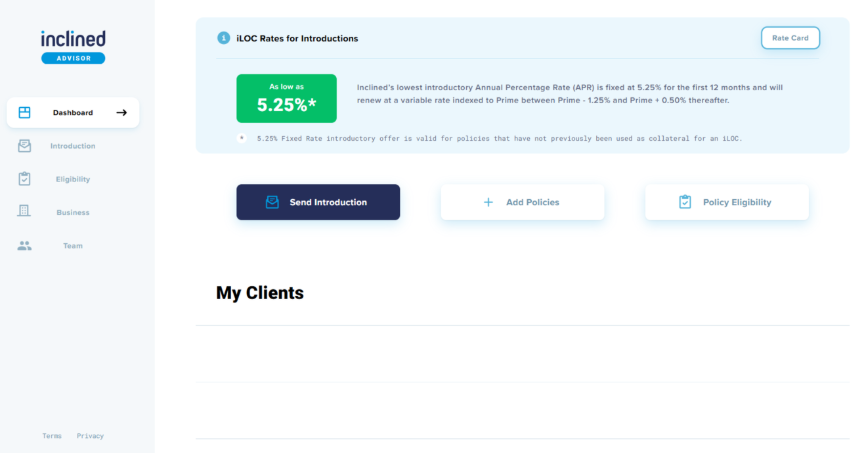
Applications can be submitted directly by clients or via an introduction from the advisor’s dashboard (see below sample) at Inclined.com:
Lines may be activated in as few as ten business days. A minimum FICO score of 620 or higher is required, but there is no income verification. Importantly, any outstanding loan balance is not reported to credit bureaus since the line is fully cash secured.
There are no fees to apply for, open or maintain the line, and the minimum credit limit is just $5,000 in most states. The iLOC is also an “evergreen” line, meaning that it never needs to be renewed and will stay active indefinitely—providing a potentially invaluable, long-term source of liquidity for the client.
Ultimately, the success of insurance-backed lines like Inclined’s iLOC is not merely a matter of advisors, policyholders and lenders being willing to take the initiative. In the end, carriers must also be on board to partner on a lightweight data-feed integration with Inclined’s pre-configured tech platform to facilitate seamless support across a full range of product types.
But, as with all institutions, change can be arduously slow. A groundswell of support from advisors may be the necessary catalyst for carriers to embrace the changing technological landscape—not only to give clients better access to their cash value, but also to give advisors another tool to position with prospects to help increase production.
The line of credit could be particularly useful for PPLI policies allocated to illiquid IDFs, once they get there.
Joseph,
This is an interesting angle I had not considered, but ties in with Bobby’s recent article on PPLI. I am sure that a lot of those illiquid assets would be much harder to borrow against outside the life insurance wrapper!
Joseph- It’s unlikely that iLOC will ever lend against an Illiquid private equity or closely held business interest inside an offshore PPLI policy.
I think it’s a wonderful and natural extension for iLOC to be available as a provision for traditional domestic PPLI. That has legs!
Jason Kurchner